Medline Industries pulls in over $20 billion in annual revenue — yet most people have no idea whether the company makes money. That’s the strange reality of dealing with one of America’s largest private corporations. The scale is hard to miss, but the financials stay out of public view.
Blackstone’s $34 billion acquisition in 2021 was one of the biggest leveraged buyouts in history. Since then, questions about Medline’s financial performance have grown louder. Investors, suppliers, and potential partners all want answers.
So, are they profitable — or just big? That’s the right question to ask. Below, we break down the numbers, the business model, and what the available data tells us.
How Does Medline Make Money?
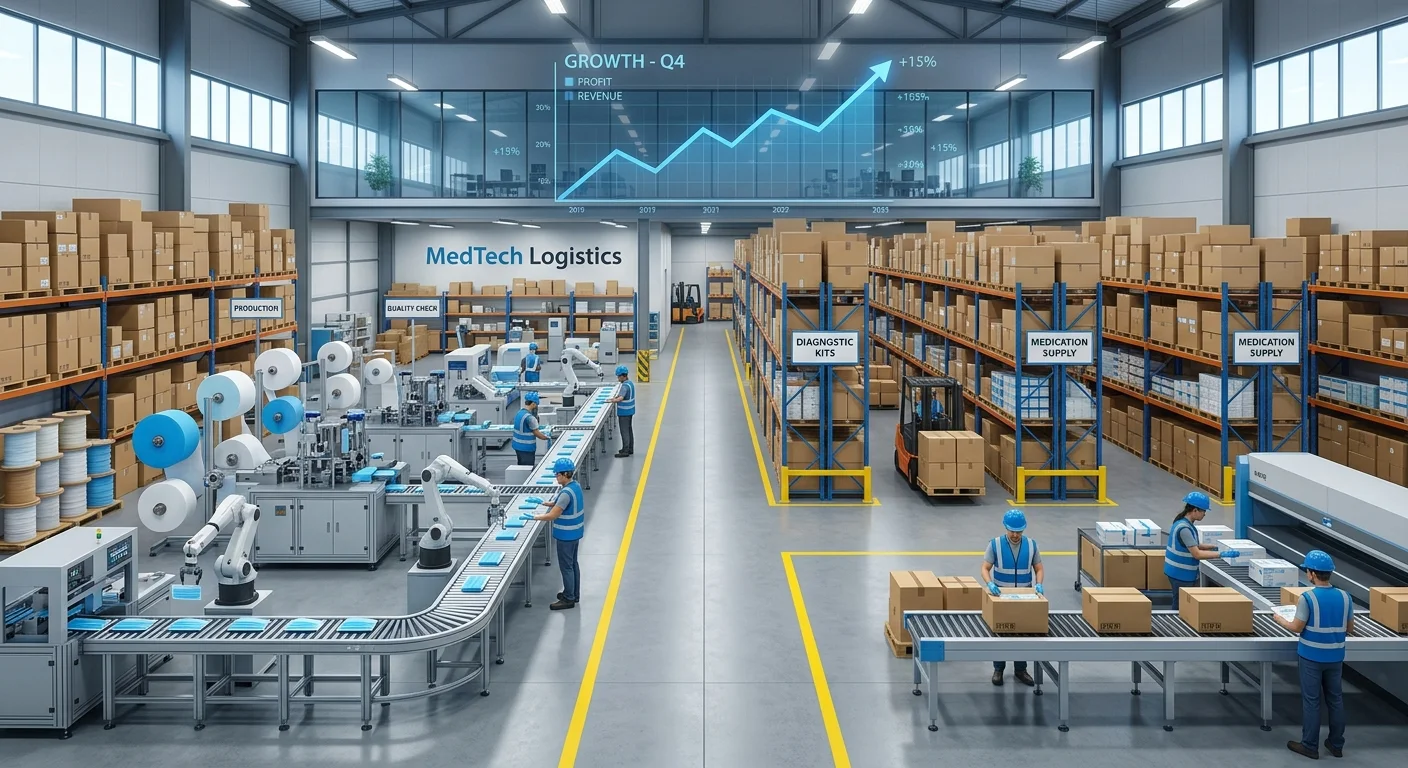
Medline runs two businesses at once — and the real power comes from where they overlap.
One side manufactures. The other distributes. Together, they build a self-reinforcing machine that generates billions in recurring revenue. Most people assume other companies dominate this space. They don’t.
Here’s how it works.
The Dual-Engine Model
Medline’s $25.5 billion in net sales (FY 2024) comes from two distinct segments:
-
Supply Chain Solutions (Distribution): ~53% of total revenue. In Q1 2026, this segment posted $3.88 billion in net sales, growing 15% year-over-year.
-
Medline Brand Manufacturing: ~47% of total revenue. Q1 2026 net sales reached $3.46 billion, up 6.2% YoY.
Those numbers look close on the surface. The profit margins tell a very different story.
The distribution segment earns a 4.8% EBITDA margin. The manufacturing segment earns 22.1%. That’s a 5x gap — and it explains everything about how Medline thinks about money.
The Prime Vendor Lock-In
The distribution side isn’t just about moving boxes. It’s about becoming indispensable.
Medline signs prime vendor agreements with hospitals, nursing homes, and surgery centers. Under these contracts, a health system commits to sourcing 70–90% of its medical-surgical supplies from Medline. That creates predictable, recurring volume — the kind of revenue a CFO can plan around three years out.
Here’s the strategic layer: Medline uses 145,000+ third-party SKUs as the entry point. Once Medline becomes your primary distributor, it cross-sells 190,000+ proprietary Medline-branded products — the items that carry that 22% margin.
It’s distribution as a Trojan horse for manufacturing profits.
Where the Margin Lives?
Look at what happens at the account level with a large hospital system:
-
Medline supplies high-volume third-party items — branded devices or commodities — at thin distribution margins.
-
Then it swaps in its own gloves , gowns , wound dressings, and surgical kits where possible. That captures manufacturing margin instead of paying it to someone else.
-
It also sells procedure-specific custom kits — surgical trays that bundle 20–40 consumables into one line item. These kits price at a premium to the sum of their parts, turning convenience and reduced complexity into profit.
Add fee-based supply chain consulting, inventory management services, and a growing e-commerce channel through Medline.com. The revenue picture gets far more varied than what most people expect from a company they assume “sells medical supplies.”
How This Compares to Pure Distributors?
Cardinal Health and McKesson are strong companies. Both earn single-digit EBITDA margins on distribution — because that’s what distribution-only businesses do.
Medline’s hybrid model changes the math:
|
Segment |
EBITDA Margin |
|---|---|
|
Distribution (Supply Chain Solutions) |
~4.8% |
|
Manufacturing (Medline Brand) |
~22.1% |
|
Blended overall |
Well above pure distributors |
That gap is why Blackstone’s $34 billion acquisition made sense. It’s also why Medline’s post-IPO valuation sits at $54 billion. Investors aren’t paying for a logistics company. They’re paying for a manufacturing business that uses logistics to defend its market position.
Medline serves over 90 of the top 100 U.S. hospital systems. With that level of contract coverage, the recurring revenue isn’t just large — it’s locked in by structure.
Is Medline Profitable?
The short answer is yes. The more interesting answer is how — and what the numbers reveal about a company that never has to show you its books.
Medline files public debt disclosures after its post-acquisition bond issuance. That gives us real data to work with. And Q1 2026 tells a clear story.
The Numbers That Matter
In the quarter ended March 28, 2026, Medline posted:
-
Net sales: $7.4 billion
-
Net income: ~$200 million (a 3.3% net margin)
-
Adjusted EBITDA: $776 million (a 10.6% margin)
-
Operating cash flow: $412 million
-
Diluted EPS: $0.16 GAAP / $0.33 Adjusted
That operating cash flow figure deserves a closer look. At $412 million in a single quarter, Medline generates more cash from operations than its net income alone suggests. The gap — $412M versus ~$200M — comes from non-cash charges like depreciation and amortization. These boost cash flow above the accounting profit line. Put simply: the business turns accounting profit into real cash at a strong rate.
That’s not a given. It’s a sign of structural health.
Where Medline Sits Against Industry Benchmarks?
Large healthcare supply companies typically run a 2–5% net income margin and an 8–15% EBITDA margin. Medline’s Q1 2026 results — a 3.3% net margin and 10.6% Adjusted EBITDA margin — sit right inside those ranges.
Not exceptional. Not distressed. Stable and consistently profitable.
That matters if you’re evaluating Medline as a partner or vendor. A company that hits normal industry profitability ranges and generates positive cash flow is financially stable by design — not by luck.
The One Honest Caveat
Profitability isn’t under pressure — but margins are. Adjusted EBITDA dropped from $868 million in Q1 2025 to $776 million in Q1 2026. That’s a year-over-year decline of $92 million, or 10.6%.
Two factors drove the compression:
-
Higher cost of goods sold , partly from tariff impacts
-
Increased operating expenses tied to onboarding new customers
Revenue growth and lower interest expense softened the blow. Net income stayed positive. Cash kept flowing. Still, the margin compression is real — and worth watching through the rest of 2026.
The takeaway isn’t concern — it’s context. Medline is profitable. It’s also dealing with the same cost pressures squeezing every large operator in healthcare supply. The difference is Medline has enough margin buffer to absorb that pressure without slipping into a loss.
Medline Financial Performance: What Do Public Data Show?
Private companies rarely hand you a clean financial picture. Medline is no exception — but its IPO filing process changed that. Medline filed a prospectus to go public. That document opened the books just enough to answer the question everyone had been asking: is this company profitable, or just large?
The answer, backed by real numbers, is clearly the former.
A Revenue Story Built on Consistent Growth
Medline closed 2025 with $28.4 billion in net sales — up 11.5% from $25.5 billion in 2024. The year before that showed 9.8% growth from $23.2 billion in 2023. Stack those two years together, and you get 22.4% total revenue growth over 24 months. For a company already operating at this scale, that’s not incremental progress. That’s a structural growth engine running at full capacity.
The average annual revenue growth rate sits at 12.2%. Most healthcare companies half Medline’s size would envy that pace.
What the Margin Stack Looks Like?
Revenue growth is easy to chase. Profitable revenue growth is harder to sustain. Medline’s financials tell an interesting story here:
|
Metric |
2025 Full-Year |
|---|---|
|
Net Sales |
$28.4 billion |
|
Gross Profit |
$7.52 billion |
|
Gross Margin |
26.4% |
|
Operating Income |
~$2.2 billion |
|
Adjusted EBITDA |
$3.5 billion |
|
Adjusted EBITDA Margin |
12.2% |
|
Net Income |
~$1.16–1.20 billion |
|
Net Margin |
4.1% |
A 26% gross margin reflects real manufacturing leverage — not just logistics throughput. The $3.5 billion in Adjusted EBITDA draws the most attention from analysts and private equity observers. It shows the true operating earning power before debt service and accounting adjustments.
The Earnings Trajectory Is the Real Story
Revenue grew 22.4% over two years. Net income grew 4–5 times over the same period — from $234 million in 2023 to $1.16–1.20 billion in 2025.
That gap matters. Earnings growing faster than revenue signals margin expansion, not just scale. Medline’s average annual earnings growth rate of 44.2% far outpaces the medical equipment industry average of 13.6%. The company isn’t just getting bigger — it’s pulling more profit from every dollar of revenue.
Where the Profits Come From?
Not all of Medline’s revenue is created equal. The segment breakdown makes that clear.
The Medline Brand segment (proprietary manufactured products) makes up 48.3% of total net sales but drives 80.6% of total Segment Adjusted EBITDA. The remaining 51.7% of revenue — the distribution and third-party supply side — produces just 19.4% of segment profit.
That’s the most important number in Medline’s financial story. Less than half the revenue carries more than four-fifths of the profit. That concentration shows you where Medline protects its margins. It also explains why growing the branded product line sits at the top of every strategic decision.
You might be evaluating Medline as a potential partner, a supplier, or just want to understand how a large private business operates at this level. Either way, the public data points to the same conclusion:
-
Strong and consistent revenue growth
-
A core business that generates profit at high margins
-
Earnings expanding well ahead of the broader industry
The numbers don’t tell a complicated story. They tell a clear one.
Medline vs McKesson vs Cardinal Health: Profitability Comparison
Three companies. One industry. Very different profit stories.
McKesson generated $359 billion in revenue in FY2025. Cardinal Health pulled in $222 billion. Medline sits at $31–32 billion. On pure scale, Medline isn’t close to the other two.
But size and profit are not the same conversation.
The Margin Gap Is the Whole Story
Line up the EBITDA margins side by side. The picture shifts fast:
|
Company |
Revenue (FY2025) |
EBITDA Margin |
Net Margin |
|---|---|---|---|
|
Medline |
~$31–32B |
~13% |
~4.7% |
|
McKesson |
$359.1B |
~2% |
~0.9% |
|
Cardinal Health |
$222.6B |
Low single digits |
~0.7% |
McKesson earns $5.25 billion in EBITDA on $359 billion in sales. That’s a 2% EBITDA margin. Cardinal’s picture looks similar. In Q1 2026, Cardinal’s net income dropped 25.2% year-over-year while peers grew at 25%.
Medline runs at ~13% EBITDA. It earns more operating profit per dollar of revenue than either of its much larger competitors. That’s not a rounding error. That’s a different business model at work.
Why the Economics Are So Different?
McKesson and Cardinal are pass-through distributors. They move branded products from manufacturers to hospitals and take a thin fee for doing it. Distribution fees often run at less than 1% of purchase value. That means McKesson can operate at a negative ~6% margin on distribution alone, before manufacturer rebates and back-end fees cover the loss.
Medline’s profitability doesn’t rest on distribution fees. It rests on private-label ownership.
70–80%+ of Medline’s revenue comes from Medline-brand manufactured products — gloves, gowns, wound care, surgical kits. The company captures manufacturing margin straight from production, instead of passing it up to a brand owner. That structural difference explains the full gap between a 2% and a 13% EBITDA margin.
The Account-Level Economics Make This Concrete
Medline tracks account profitability against a clear threshold:
-
Less than 30% Medline-brand mix in a customer’s basket → the account runs at a loss
-
30% or more → the account turns profitable
-
Around 40% Medline-brand share → a “really good, mature, profitable account” with strong long-term economics
McKesson and Cardinal don’t have this lever. No significant private-label portfolio means no way to shift the margin structure at the account level. Every extra dollar of volume runs through the same thin distribution economics.
Profit Growth: Where Medline Stands Out
The growth trajectory tells just as much as the current numbers.
Medline moved from a $25 million net loss in 2022 to $1.2 billion in net profit by 2024. That’s a $1.175 billion swing in two years, on revenue growth of just 20%. Earnings grew far faster than sales. That’s the clearest sign of margin expansion, not just added scale.
McKesson grew net income 172.6% between 2021 and 2025. That’s a strong number. But it started from a very low margin base and still lands at 0.9% net margin. Cardinal’s earnings are moving up, but recent quarters have stayed volatile compared to peers.
What This Means for Suppliers and Partners?
You’re evaluating these three companies as potential partners or customers. The margin structure has real, practical implications:
-
For private-label or margin-sharing programs : Medline’s 13% EBITDA leaves real room to negotiate pricing and stay profitable. McKesson and Cardinal operate at 1–2% EBITDA. They have almost no room to move on margin without cutting into already-thin returns.
-
For pure distribution RFPs : McKesson and Cardinal tend to bid hard on commodity pass-through SKUs. Their scale advantages dominate there. Medline competes strongest where branded mix is high, and it can push proprietary products into the basket.
-
For credit and stability assessment : McKesson’s $3.3 billion in net income and steady margin profile make it the most predictable of the three. Medline’s private ownership adds some opacity. But its profit trajectory — from a loss to $1.2B in two years — points to real structural strength.
The comparison comes down to what you’re measuring. By revenue, McKesson wins by a wide margin. By profitability per dollar of sales, Medline isn’t just competitive — it’s in a different category altogether.
Is Medline Financially Stable for Long-Term Partnerships?
Stability in business isn’t about perfection. It’s about resilience. On that measure, Medline’s financial picture looks solid — with a few things worth watching before you sign a multi-year agreement.
Here’s the honest read.
The Signals That Say “Yes”
The numbers that matter most to a potential partner point in the right direction:
-
$28.4 billion in 2025 net sales , growing 12% year over year
-
$3.5 billion in Adjusted EBITDA — up 3.2% despite a year of cost pressure
-
~$1.2 billion in net income and ~$1.3 billion in free cash flow
-
2026 guidance projecting 8–9% organic growth and $3.5–3.6 billion in EBITDA
That free cash flow number carries real weight. A company generating $1.3 billion in annual free cash flow can pay down debt, fund daily operations, and absorb unexpected shocks. It doesn’t need to make painful cuts that ripple through supplier and partner relationships.
Fitch upgraded Medline’s credit rating to BBB- with a Stable outlook. That’s the lowest investment-grade tier — not a flashy rating. But investment-grade status signals that Medline’s capital structure has reached a level of discipline that credit analysts trust for long-term commitments.
The Debt Picture: Improved, Not Resolved
After the IPO, Medline paid down $4 billion in debt. That brought the leverage ratio down from 4.9x to 3.1–3.25x net debt/EBITDA. Fitch expects that figure to stay below 3.75x over the medium term.
That said, $12.6–12.8 billion in remaining debt — secured for the most part, with maturities in 2028–2029 — means leverage is still a real factor. It’s not a footnote you can ignore.
What to Watch Before Committing Long-Term?
Two risks deserve your attention:
-
Tariff exposure: Management flagged a potential $150–200 million income hit in fiscal 2026 from trade policy and imported input costs. That’s a real drag on a ~$1.2 billion earnings base.
-
Margin compression: Q4 2025 net income fell 37.7% year over year, driven by higher COGS and operating costs.
Neither risk is a dealbreaker. Both are worth factoring into your contract terms.
The bottom line: Medline is a strong, cash-generating supplier with a credible investment-grade profile and improving leverage. For most long-term supply agreements, that combination gives you solid ground to stand on. Keep an eye on the debt maturity timeline and tariff trajectory as 2026 plays out.
FAQ About Medline’s Profitability and Business
People ask the same questions about Medline. The wording changes, but the core questions stay the same. Here are the answers, pulled from real numbers.
Are Margins Growing or Shrinking?
Shrinking. And worth watching. Operating margin slipped from 8.4% to 7.8% year over year. Gross margin dropped 0.9 percentage points. Q1 2026 adjusted EBITDA fell 10.6% year-over-year. Two main culprits drove that drop:
-
An $85 million tariff hit
-
Higher operating expenses
The business is still profitable. But the margin trend is worth a close look before 2026 wraps up.
How Healthy Is Medline’s Balance Sheet?
Debt sits at $12.57 billion — a heavy load. But the numbers around it hold up:
-
4.41x current ratio
-
$2.24 billion in cash on hand
Short-term liquidity is strong. Debt service stays manageable, backed by $316 million in free cash flow per quarter.
Is Medline Getting More Efficient Over Time?
One metric tells the story: Return on Capital Employed jumped 73.3% — from 0.08 to 0.14 — in a single year. That’s a sharp move. Revenue grew 10.7% in Q1 2026. Organic sales guidance for the full year was raised to 8.5–9.5%. Medline isn’t just getting bigger. It’s pulling more profit from every dollar it puts to work.
Conclusion
Medline doesn’t post its financials on a stock ticker — but the numbers that have come out tell a clear story. A company valued at over $34 billion. Generating $20+ billion in annual revenue each year. Backed by Blackstone’s institutional weight. You don’t reach those numbers by accident.
Medline builds toward profitability — through vertical integration, private-label dominance, and a distribution network designed for scale.
For investors, analysts, or potential partners sizing up Medline’s financial health, the evidence is hard to ignore:
-
The business stands on a solid structural foundation
-
It runs with sharp strategic discipline
-
It’s built to win over the long term
So what’s your next move? Evaluating Medline as a supplier or partner? Use this analysis as your starting point — then dig deeper with industry-specific due diligence. Just trying to understand how the quiet giants of healthcare make money? You’ve just met one of the most interesting ones.
The best businesses don’t always need a spotlight. Sometimes, they are the infrastructure.